
Your Roof, Your Barn, Your Day in Court: 3 Texas Insurance Bills
HB 1116, 1117 and 1118 would change Texas property insurance claims: two years to recover depreciation, no forced arbitration, opt-in outbuilding coverage.
By Ryan Nichols
- 17 total reach
- 0 reading now•0 active 24h
- 0 shares•0 inbound
- 0 comments
Your roof claim. Your barn. Your day in court.
Plain-English summary
Three insurance bills hit the Texas House filing list today. All three were filed by Rep. Morgan. All three are about what happens after a storm, when you file a claim and wait on a check.
HB 1116 gives you two years to collect the depreciation your insurer held back.
HB 1117 voids the fine print that forces you into binding arbitration before you can go to court.
HB 1118 changes how your policy handles the shop, the barn, the detached garage, and every other building on your land that is not the house.
Two of these are plain wins for policyholders. One needs a hard look before anybody votes. Here is the receipt on all three.
Why it matters
In East Texas, a storm does not ask permission. Hail, straight-line wind, a pine through the roof. Then comes the adjuster, the estimate, and the first check that is smaller than the bill.
DOCUMENTED INFERENCE: Community Impact reports Texas has some of the highest home insurance costs in the nation. If families are paying top dollar, the claim had better pay like it.
Out here, a lot of what we own is not the house. It is the shop where a man makes his living. The barn. The pole shed over the tractor. If coverage for those buildings changes, rural Texas feels it first.
The receipt
FACT: HB 1116 says a policy covering property damage "must permit an insured to recover depreciation withheld from a claim for a covered loss until the second anniversary of the date the insurer issues a claim payment for the loss." That withheld depreciation cannot be counted as the insurer's defense costs or deducted from defense coverage limits.
FACT: HB 1117 makes a binding arbitration clause in a property and casualty contract "void and unenforceable" if it does any of these:
- Forces you to arbitrate before you can seek a court remedy.
- Keeps the courthouse open for the insurer but not for you.
- Waives your rights under Insurance Code Chapters 541 or 542, the Deceptive Trade Practices Act, common law, or other consumer protection law.
- Shortens a deadline Texas law already sets.
- Sends a Texas resident out of state to arbitrate.
- Charges an arbitration fee substantially greater than a district court filing fee.
FACT: Under HB 1117, an agreement to arbitrate only holds if it is made after the dispute starts, separately signed by every party, and gives both sides equal rights.
FACT: HB 1118 says a home or commercial property policy "is not required to provide other structures coverage." An insurer may include that coverage only if the insured "affirmatively elects" it and it is listed on the declarations page or an endorsement. A policy without it must say on the declarations page that other structures are not covered.
FACT: All three bills take effect September 1, 2027, and apply to policies issued or renewed on or after January 1, 2028. Bill histories: HB 1116, HB 1117, HB 1118.
What Ryan says
RYAN STATEMENT: If you bought replacement cost coverage, the depreciation they hold back is money you are owed once the work is done. After a big storm, getting a roofer out can take a while. Two years to collect is common sense. I support HB 1116.
RYAN STATEMENT: Arbitration is fine when both sides pick it after the fight starts. It is not fine when it is buried in a policy you never negotiated, it shuts the courthouse door on you, and it leaves it open for the company. HB 1117 says the rules have to be the same for both sides. Same contract, same rule. I support it.
RYAN STATEMENT: HB 1118 is where I slow down. I like the notice. Put it on the declarations page in plain sight. But read it again. It says the policy is not required to cover your other buildings, and the coverage only exists if you opt in.
DOCUMENTED INFERENCE: On my reading of the text, a family that renews without checking a box could lose coverage on the barn or the shop and find out after the storm. I want the author and the committee to answer that in the hearing. Who gets told at renewal? How? And what happens to every policy that covers those buildings today?
RYAN STATEMENT: Clear is good. Clear and quietly gone is not.
What this does not prove
It does not prove any of these bills will get a hearing, a vote, or a signature. Filing day is the start, not the finish.
It does not prove any insurer has done anything wrong to any person. These are bills about policy terms, not charges against anyone.
It does not prove HB 1118 will cut anybody's coverage. That depends on how the bill is amended and how the Texas Department of Insurance writes rules under it.
It does not tell us who asked for these bills or why. The text does not say.
What it does prove
FACT: A Texas House member filed three bills today that change claims, courtroom access, and outbuilding coverage for Texas policyholders.
FACT: The arbitration bill names the exact clauses it would void. The depreciation bill names a two-year window. The outbuilding bill names an opt-in and a notice.
That is the text. That is the record.
The bottom line
Pay the claim. Keep the courthouse open to both sides. And do not let a family lose the barn because of a box nobody checked.
Read your declarations page tonight. Know what is covered before the next storm does it for you.
Do not threaten anyone. Do not harass anyone. Do not contact anyone in my name. Read it. Share it. Send receipts, evidence, witnesses. Put eyes on the record.
You made it to the end
Most people quit at the headline. You didn’t.
So don’t stop here. Pick one.
Read the book
Fighting Shadows is the whole story in my own words: the road into January 6, the D.C. jail, and the fight to get the record out.See the book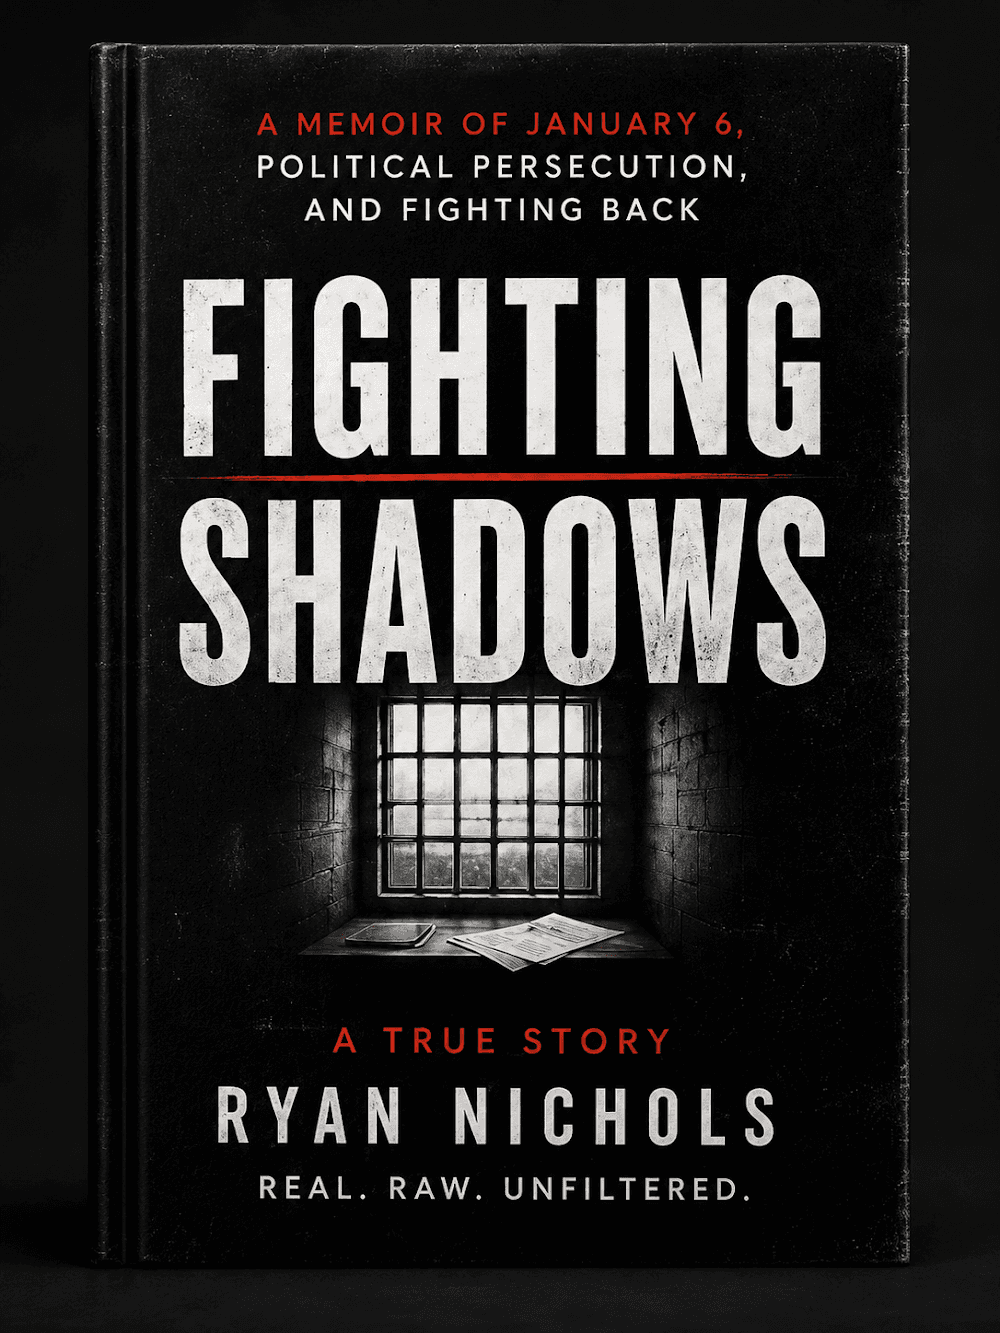
Follow the case
The record is still being written. Get one email when something new drops on it.
Hire Ryan
I built this site. Want one that brings your business real leads? Start with a free 30-minute call.See the services
Tap how this hits you. No signup, everyone sees the count
17
Views
0
Likes
0
Comments
0
Shares
Share it. Every share puts more eyes on the record.
Comments
Speak here
Create an account to comment.
This is where people can say what gets buried or cancelled elsewhere. Comments are signed-only, moderated, and tied to a real profile so the record stays usable.
No approved comments yet. Create an account and put the first opinion on the record.